Key takeaways
- The SEC has created a five-year trial that lets qualifying venues trade real tokenized U.S. stocks through smart contracts and liquidity pools without registering as full national securities exchanges.
- Eligible tokens must preserve the rights attached to the underlying shares, including dividends and voting rights. Products that only mirror a stock's price are outside this relief.
- The software must be public and auditable and run on a public blockchain, but access to each venue remains permissioned.
- Strict listing and volume caps apply, and an issuer can object when an unaffiliated third party wants to tokenize its stock.
- This is a controlled regulatory experiment, not a permanent rewrite of U.S. securities law or an open invitation to trade every stock through DeFi.
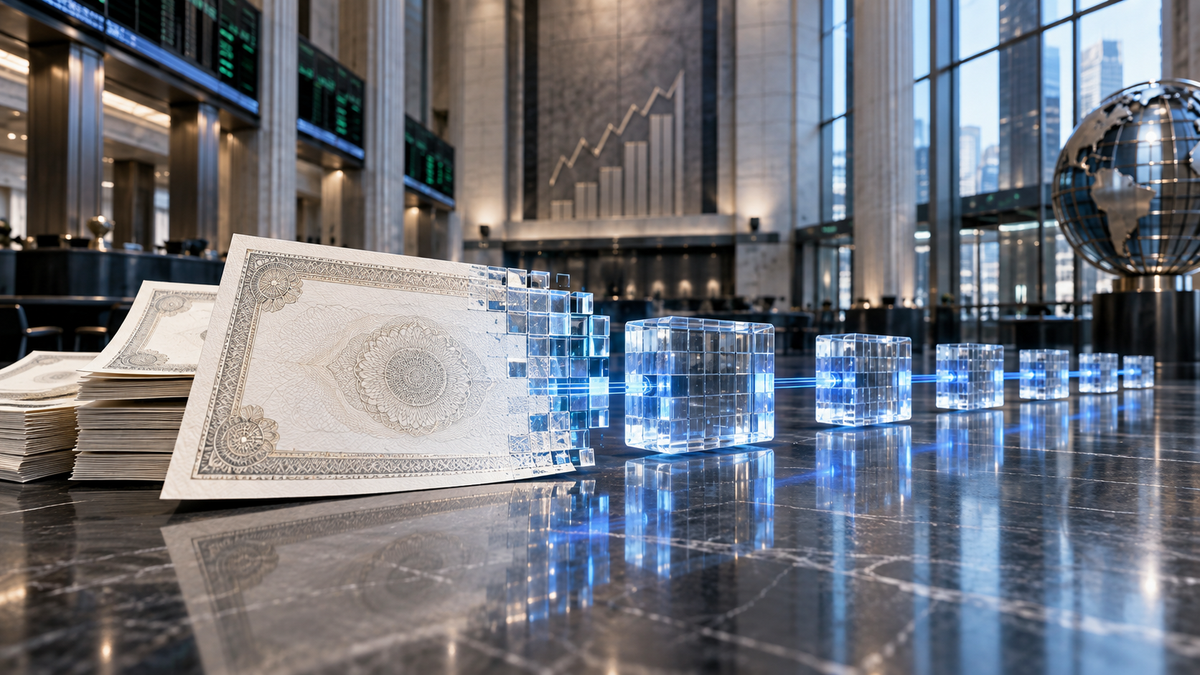
Most products described as tokenized stocks have historically offered economic exposure to a share price without necessarily making the buyer a shareholder. The U.S. Securities and Exchange Commission is now testing a different model: putting genuine stock ownership, with the rights that ownership carries, onto blockchain infrastructure.
On September 17, 2026, the SEC issued its Innovation Exemption. The order gives qualifying Tokenized Securities Venues, or TSVs, temporary relief to facilitate trading in tokenized National Market System stocks through automated market makers and liquidity pools. The exemption runs until September 17, 2031 while the Commission gathers evidence and considers durable rules.
What the SEC changed
A platform that brings securities buyers and sellers together can fall within the legal definition of an exchange. That framework was built around conventional market infrastructure, making it difficult to test blockchain systems that execute trades through smart contracts rather than a traditional order book.
The new order offers two forms of conditional relief. A compliant TSV can operate without being treated as a national securities exchange during the trial. Certain firms that contribute proprietary capital to its liquidity pools can also receive relief from the Exchange Act definition of a dealer.
What has not changed: Federal anti-fraud and anti-manipulation rules still apply. Participants must meet the order's disclosure, recordkeeping, technology and market-integrity conditions.
Real tokenized stock versus synthetic exposure
The legal substance matters more than the token label. The SEC's framework is designed for a token issued by the company itself or a qualifying third-party structure that conveys rights connected to real underlying stock. It excludes instruments that merely promise a return linked to the stock's price.
| Question | Eligible tokenized stock | Synthetic stock-linked product |
|---|---|---|
| What does the holder own? | Stock or a qualifying entitlement backed by underlying shares | A claim against the product issuer or derivative exposure |
| Voting and dividends | Must preserve the equivalent rights and privileges | May be absent or recreated contractually |
| Counterparty risk | Can still exist, especially in third-party custody structures | Usually depends heavily on the issuer's ability to perform |
| Covered by this exemption? | Potentially, if every condition is met | No, when it is only synthetic exposure |
A trading halt in the conventional market must also apply to the tokenized counterpart. The objective is to modernize the representation and movement of ownership without removing the protections and rights that make the instrument a share.
How the market design works
A TSV may use an automated market maker rather than matching each buy order with a sell order. Liquidity providers place tokenized shares and settlement assets into pools, while public, auditable software determines how trades execute and how prices are formed.
The underlying network must be public and permissionless. The venue itself is not. A TSV controls admission and sets standards for who may trade. It is therefore better understood as regulated market infrastructure borrowing selected tools from DeFi, not a conventional decentralized exchange listing U.S. stocks for anonymous wallets.
Supporters see a path toward more efficient settlement, interoperable ownership records and programmable workflows. The order, however, does not turn TSVs into lending or leveraged trading platforms.
The guardrails
- A five-year term: The relief expires on September 17, 2031 unless the regulatory position changes.
- Listing and volume limits: One tier allows up to 75 highly liquid names and 0.25% of average daily volume per venue. A second tier permits up to 250 names and 2.5% of average daily volume.
- Issuer objection rights: An unaffiliated tokenizer must provide 30 days' notice, and the public company can prevent its stock from trading on that TSV.
- Shareholder rights remain intact: Eligible tokens must carry the same material rights, including voting and dividends.
- Public transaction data: Price, size, time, pool address, end-of-day pool size and daily U.S. dollar volume must be available for monitoring and analysis.
- Controlled access and compliance: A TSV must be a U.S. person and meet applicable sanctions and participant-access obligations.
What it means for investors
The potential benefit is straightforward: investors could hold genuine equity through infrastructure that records transfers on a blockchain. Settlement may become more direct, ownership records more portable and future financial services easier to connect.
Blockchain does not remove product risk. Investors still need to know who issued the token, who holds the underlying shares, how ownership is reflected in official records, what happens if an intermediary fails, whether the smart contracts have been reviewed and whether there is enough liquidity to exit.
Do not buy the label: Confirm the holder's legal rights, proof of underlying shares, dividend and voting procedures, custody arrangements, redemption terms and governing jurisdiction before treating any product as real stock.
What it means for public companies
A company does not have to tokenize its own shares. A third party could create a qualifying entitlement backed by shares held through a broker or custodian. The issuer must receive advance notice and can object before that product is admitted to a TSV.
This veto helps prevent a company's securities from appearing in an onchain market it has not approved, while still leaving room for regulated intermediaries to develop new infrastructure where issuers are comfortable with the arrangement.
Why this matters
The important experiment is not merely replacing a paper certificate with a token. It is testing whether blockchain can become part of the operating machinery for trading, transfer, settlement and ownership records in the U.S. equity market.
The SEC has separately proposed modernizing transfer-agent rules to accommodate blockchain-based recordkeeping. Taken together, the initiatives address both sides of the question: how ownership may be recorded and where that ownership may be traded. The five-year window gives regulators data before they decide whether to build a permanent framework.
Frequently asked questions
Will every U.S. stock be available onchain immediately?
No. The program limits eligible venues, participants, listings and trading volume. Issuers can also object. It is a narrow trial, not a migration of the NYSE or Nasdaq to a blockchain.
Can any wallet connect and trade?
No. Although the underlying blockchain is public, TSV participation is permissioned. Investors must satisfy the venue's access requirements.
Is tokenized stock the same as cryptocurrency?
No. A tokenized share remains a security subject to securities law. The recordkeeping format changes; the legal character and regulatory obligations do not disappear.
Does the order guarantee 24-hour stock trading?
No. Blockchain can support extended availability, but actual trading hours depend on each venue and the conditions that apply to it.
Does this directly change Thailand's stock market?
No. The order applies to qualifying U.S. venues and NMS stocks. It is still relevant internationally as a practical model for testing blockchain inside regulated capital markets.
Conclusion
The SEC's Innovation Exemption is significant because it treats blockchain as potential market infrastructure rather than decorative packaging. Yet it does so within clear boundaries: real shareholder rights, controlled access, issuer protections, transparent software and limited market size.
For investors, the right question is not simply whether an asset is onchain. It is what legal right the token represents, who stands behind the underlying shares and how that right can be enforced. New settlement technology does not replace careful product due diligence.
Sources
- SEC: Innovation Exemption for Tokenized NMS Stock
- SEC Order and Request for Comment, Release No. 34-106402
- SEC Chairman Paul Atkins: A Bridge Toward Durable Rulemaking
- SEC Staff Statement on Tokenized Securities
- CoinDesk: Real Stocks Are Finally Coming on Blockchain
Information reviewed on September 19, 2026. Regulatory conditions and services may change. Written by Bank for general education only; this is not legal or investment advice.
Share:
Lost Your Ledger? What Happens to Your Crypto and What to Do Next